If a card payment to one of the Canada online casinos went wrong, casino chargeback canada is the bank process this page explains.
Play responsibly. Bonus terms apply. Age restrictions depend on your province.
A chargeback is technically available for card payments to casinos. It is built for payments you did not authorise or never received. It rarely works for a normal gambling loss, because you authorised the payment and got the play. In most cases, a casino closes the account once a chargeback arrives.
You learn what casino chargeback canada claims are, the steps in order, and when the rules allow a dispute or not. A clause table shows casino terms, and another compares payment methods. You see what the casino does next and what to try first. Worked C$ examples, scam warnings and a FAQ follow.
This page explains how the process works and is not legal advice.
Casino chargeback canada: what does the phrase mean?
The phrase means asking your bank or card issuer to reverse a casino payment, and the bank, not the casino, decides. Vellis, a blog for casino operators, defines a chargeback as a player’s request that the card issuer undo a casino charge.
Player Protection Legal, a UK law firm, sells a no-win-no-fee service. It says chargebacks were designed for unauthorised or undelivered purchases, not to undo legitimate gambling losses.
Three kinds of pages cover casino chargeback canada, and each one cares about a different thing.
- Bank complaint bodies, such as OBSI, care about the dispute between a customer and the bank.
- Law-firm pages, such as Player Protection Legal, care about whether a payment was unauthorised or undelivered.
- Payment blogs, such as Vellis, care about the evidence a casino can send to support the charge.
Keep that in mind when you read each one: Vellis writes for casino operators, not for players.
Who decides a chargeback on a casino payment?
In a casino chargeback canada case, the card issuer or bank decides, and the casino can send evidence for the charge. OBSI says the bank investigates to see whether the request is valid. Here is who does what.
- You ask your bank or card issuer to reverse the payment.
- The casino learns of the claim, and Vellis says it can send proof that the charge was legitimate.
- The bank investigates and decides, and WealthNorth says a chargeback is the reversal when the issuer sides with the cardholder.
- In a casino chargeback canada case, OBSI does not investigate the casino. It only reviews disputes between a consumer and a bank.
Our Visa review says a chargeback rarely wins for gambling, since you approved the payment and got the service. Our credit card review calls a casino chargeback canada claim a poor remedy, since operators close the account on receipt.
If the casino itself looks like a scam, start with our guide to casino scams or our guide to blacklisted casinos.
Casino chargeback canada: what are the dispute steps in order?
The three steps run in order: talk to the casino first, then ask your card issuer, then the bank investigates and decides.
A casino chargeback canada dispute is a card dispute, so card rules set the order. OBSI says refunds and chargebacks follow strict procedures and timelines, so keep track of the dates.
Step 1: talk to the casino first
OBSI says most cardholder agreements and legal rules tell you to go to the merchant first. In this case, the merchant is the casino. OBSI also says laws, regulations and card network rules can protect you when a card purchase goes wrong.
Player Protection Legal, a UK law firm blog, says banks prefer that you try the casino first. OBSI says strict time limits apply, so write to support soon and keep the replies. If a rule is unclear, our guide to reading casino terms shows how to read it.
Step 2: ask your card issuer
If talking to the casino fails, OBSI says you can ask your card issuer for a refund or a chargeback. In most cases, the issuer is a bank.
OBSI says that for a problem with the merchant, the bank sends a chargeback request through the card network. Examples of networks are Visa, Mastercard and American Express. That makes a casino chargeback canada claim a matter for the network’s own process.
Step 3: the bank investigates and decides
OBSI says the bank refunds the charge to your card in most cases while it investigates. Vellis, a blog written for casino operators, calls this refund temporary. In most cases, the process takes weeks, Vellis says. The bank has the final say.
OBSI says the card network brings in the casino’s bank, which asks the casino for information in most cases. In a casino chargeback canada case, Vellis says the bank then decides whether the refund stays or goes. OBSI says the bank reverses it later if you were not entitled to it.
What proof does a bank ask for in a casino chargeback canada case?
The proof is the paper trail behind your reason for the dispute, and OBSI and our review name the items below.
- The card statement that shows the disputed charge.
- The original receipt, contract, purchase order or invoice from the merchant.
- Emails or other messages that show you tried to fix the problem with the casino.
- Reasons to believe fraud happened, if fraud is your reason.
- Screenshots, payment records and chats, which our review says to keep from the moment trouble starts.
Player Protection Legal says to collect the documents before you contact the bank. In a casino chargeback canada case, OBSI says you need to cooperate with the bank’s investigation, because most card agreements require it. Give the bank your information within reasonable timelines and answer its questions truthfully.
When does a casino chargeback canada claim fit?
A claim fits when you did not authorise a payment, the casino overcharged you, or it never delivered what you paid for. OBSI lists these reasons for disputed credit card charges. A casino chargeback canada claim needs one of them.
- Lost or stolen card: another person used your card and you did not agree to the payment.
- Fraud: you were defrauded by the merchant itself.
- Wrong amount: the merchant charged more than you authorised.
- Billing error: the charge on your statement does not match what happened.
- Not delivered: the merchant did not deliver what you paid for.
In most cases, OBSI says, a fraud or stolen card problem ends in a refund under the network’s zero liability policy. Our Visa casino guide adds that unauthorised transactions are recoverable under network rules.
Our credit card casino guide says to tell the issuer at once when another person uses your card without asking. OBSI also says the outcome rests on the evidence that each side can show about what happened.
Player Protection Legal names two more cases. It says an unlicensed or scam casino deposit warrants a chargeback in certain cases, and that withheld winnings give grounds for one. The bank still makes the call on a casino chargeback canada claim, and nothing is promised.
When does a chargeback not fit a casino loss?
A chargeback does not fit a plain gambling loss, regret or a slow withdrawal, and a broken casino rule is unlikely to succeed. None of these gives a casino chargeback canada claim a sound basis.
- A fair loss: Player Protection Legal says money lost on a bet or game cannot be charged back.
- Regret: our credit card casino guide says changing your mind about a deposit gives no grounds.
- A broken casino rule: if a casino refuses payment over bonus abuse or multiple accounts, Player Protection Legal sees little chance.
- A slow withdrawal: Player Protection Legal says a payout slower than you want is not a dispute reason by itself.
- A payment you authorised: if the casino delivered the service, our guide says the dispute fails on the facts.
Vellis and PayShield, two blogs written for casino operators, call a claim that a payment you made was unauthorised “friendly fraud”. Vellis describes a player who makes a real deposit, loses, then tells the bank the charge was not authorised.
PayShield adds that players sometimes dispute valid payments with their bank instead of asking casino support. A casino chargeback canada claim that says a real payment was unauthorised is plain fraud, and this page never suggests it.
Vellis says misuse of chargebacks counts as fraud and can bring account bans or legal consequences. Player Protection Legal says misuse can end in a closed bank account or a blacklist with payment providers. An honest casino chargeback canada dispute needs a real reason.
Casino chargeback canada: what does merchant code 7995 change?
Our Visa casino guide says gambling operators carry code 7995, which lets an issuer block the whole industry with one rule. The code covers betting, such as lottery tickets, casino gaming chips and wagers.
Canadian issuers set their own policies: certain issuers approve casino payments, others decline them, and others bill cash advance rates. So a casino chargeback canada claim begins with a question to your own issuer.
Card networks add rules of their own. Vellis says Visa and Mastercard set specific rules for gambling payments and apply higher scrutiny. Player Protection Legal, a UK law firm blog, says certain card terms exclude gambling from dispute eligibility.
Our Mastercard casino guide quotes Chargeback Gurus on reason codes for a casino chargeback canada dispute. Code 4837, No Cardholder Authorization, belongs to the fraud category. Code 4849 is Questionable Merchant Activity, and code 4863 is Cardholder Does Not Recognize Potential Fraud.
Ask your issuer directly, because that is more reliable than any published list.
How long do you have to dispute a casino charge?
In most cases, OBSI says, you need to dispute a casino charge within 30 to 45 days of the statement date. Limits for a casino chargeback canada claim differ by source, so each figure below belongs to the source named.
- The Financial Consumer Agency of Canada says chequing and savings account holders get 30 days from the statement date. The agency says that holds in most cases.
- Player Protection Legal, a UK law firm blog, says most banks allow around 120 days after the transaction date.
- Our Mastercard casino guide gives the issuer 120 calendar days for the five codes 4837, 4840, 4849, 4853 and 4863.
- The same guide gives the acquirer and merchant 45 calendar days to respond to a dispute filed under those codes.
- Amex Canada gives merchants 20 days to answer, counted from the date of the inquiry letter, says our Amex casino guide.
The figures differ, and OBSI says all banks have time limits. OBSI and the agency count from the statement date, while Player Protection Legal counts from the transaction date. So do not delay, whichever count applies.
Example, not an offer: a statement is dated the first of a month, and the limit is 30 days. Counting 30 days forward lands on the thirty-first of a 31-day month. In this example, the clock on a casino chargeback canada claim ends that day.
The bank investigation after you file is a separate wait. Player Protection Legal says it takes around 30 days in most cases. It adds that complex cases take up to 90 days to reach a final decision.
Our scam guide says to move in days, not weeks, because dispute windows are limited. For a casino chargeback canada claim, the figures above belong to their sources, so check the limit with your issuer.
Casino chargeback canada: what do casino terms say?
The English terms we captured from four casinos bind the player to chargeback and cost promises, as the table below shows. Each row gives the clause, what follows for the account and who states it. Casinos with no clause quoted on this page sit in the last two rows.
| Casino | Chargeback or reversal clause as printed | What follows for the account and balance | Stated by |
|---|---|---|---|
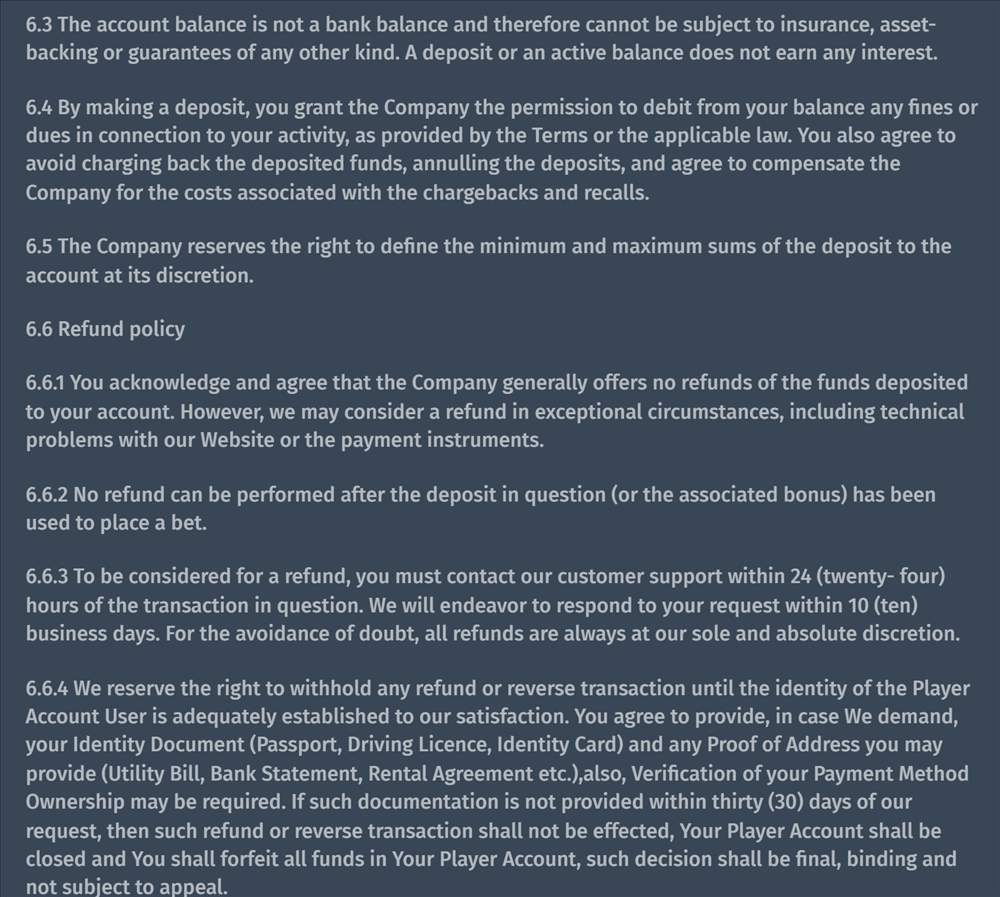
| Allyspin | Clause 6.4: no charging back deposits; player covers chargeback and recall costs | Clause 6.6.4: no ownership papers in 30 days, no refund, account closed, funds forfeited | Allyspin English terms |
| Dudespin | Clause 6.4: no charging back deposits; player covers chargeback and recall costs | Clause 6.6.4: no ownership papers in 30 days, no refund, account closed, funds forfeited | Dudespin English terms |
| Spinko | Clause 6.12: an indemnity for losses from a chargeback or deposit reversal | Player reimburses the casino in full for those losses | Spinko English terms |
| Ice Casino | Clause 8.7: suspicious or fraudulent payment, including stolen cards and chargebacks | Casino can block the account, reverse a payout and recover winnings | Ice Casino English terms |
| SpinRollz | No charging back deposits; player covers chargeback and recall costs | Clause 6.6.4: no refund papers in 30 days closes the account, forfeits funds | Our SpinRollz review |
| Legiano | Clause 6.4: no charging back or annulling deposits; customer covers chargeback and recall costs | Clause 6.6: refund requests due within 24 hours | Our iDebit guide quoting Legiano’s rules |
| Spinwinera | Terms treat a chargeback as suspected fraud | Chargebacks can lead to account termination | BetterBonus, per our review |
| V.Vegas, Zoome and OnlyWin | No chargeback clause quoted on this page | No balance clause quoted on this page | Not quoted on this page |
| Slotoro, FS Casino and Verde | No chargeback clause quoted on this page | No balance clause quoted on this page | Not quoted on this page |
The table repeats what our reviews and the casinos’ English terms pages quote. The Spinwinera lines come from a second-hand list (BetterBonus), as our review says. The casino’s own English terms page is the only final word on these clauses. The table is a guide to casino chargeback canada wording.
What do the chargeback clauses mean in plain words?
They tell the player not to charge back a deposit and say what the casino can do if a chargeback happens. In casino chargeback canada clauses, the player makes a promise and the casino lists its steps. For more on reading these lines, see our guide to reading casino terms.
Allyspin and Dudespin print the same casino chargeback canada wording in clause 6.4. The player agrees not to charge back or annul deposits and to pay the casino’s chargeback and recall costs. Our reviews quote the same promise for SpinRollz, and our iDebit guide quotes it for Legiano as clause 6.4.
Clause 6.6.4 adds a casino chargeback canada rule on refunds and reversals. The casino can ask for proof of payment method ownership. With no papers in thirty days, no refund is made, the account closes and the funds are forfeited. Allyspin and Dudespin also name recalled or disputed funds in their fraud list.
Spinko clause 6.12 says the player repays, in full, the casino’s losses from a chargeback or deposit reversal. Ice Casino clause 8.7 names stolen cards, chargebacks and other fraud. The casino can then block the account, reverse a payout and recover winnings. Both show why casino chargeback canada terms need a slow read.
Casino chargeback canada: what do three worked examples show?
The same bank process gives three different results, because the facts of each payment decide the outcome, not the process itself. The sums below are examples, not offers. Each example asks what left the card and what arrived. They do not promise any result in a real casino chargeback canada case.
Example, not an offer: a duplicate charge
A player deposits C$40, but the card is charged twice. C$80 leaves the card, C$40 reaches the casino balance, and C$40 is the extra charge. The player authorized one C$40 payment, so the second C$40 is the problem. The player asks the casino first.
In a casino chargeback canada case like this one, only the extra C$40 is disputed, not the C$40 that was credited. OBSI lists a billing error as a reason. It also lists a charge above the authorized amount. It says the bank refunds the charge in most cases while it investigates.
Result as OBSI describes it: C$40 is disputed, and the bank reverses the refund if the player was not entitled.
Example, not an offer: a deposit that never arrived
In this casino chargeback canada example, a player pays C$120 by card, but the casino balance stays at C$0. The player keeps the card statement, the payment receipt and the chat with support. A payout that fails is a different problem, covered in our declined withdrawal guide.
The sources list a statement, a receipt and emails as the records to keep. OBSI lists a merchant that did not deliver as a reason. When the merchant is the cause, the bank files a chargeback request through the card network, such as Visa or Mastercard. The player paid C$120 and received C$0.
Result as OBSI describes it: C$120 paid, C$0 received, C$120 disputed. Non-delivery is a listed reason, and the bank follows the card network’s process.
Example, not an offer: a normal losing session
A player deposits C$100, plays it and loses it. The card statement shows C$100, and the balance is C$0. The payment went through once, for the amount the player chose. The casino gave C$100 of play for C$100 paid, so nothing is missing from the deal.
In a casino chargeback canada case, Player Protection Legal says a fair loss on a game cannot be charged back. Our Visa guide says regret is not a reason either. The casino delivered the play, and our credit card guide says a dispute like that fails on the facts.
Filing a casino chargeback canada request anyway has a cost. At most operators, our credit card guide says, a chargeback on a deposit gets the account closed and the balance forfeited. With C$25 left in the account, that is C$25 lost on top of the C$100.
Result as the sources describe it: C$0 recovered, and at most operators the account closes with C$25 lost.
What does the casino do when a chargeback arrives?
In most cases the casino closes the account and forfeits the balance, and Player Protection Legal says it fights the claim with its records. Our credit card guide calls the operator’s stance adversarial and says closure comes with the balance forfeited. It also lists a flag across the operator’s payment network among the common results.
Our fast payout guide says the closure is permanent in most cases. In certain cases the player is also flagged across a payment network. Our guide to choosing a safe casino adds that the player is flagged across operator networks. It names the complaints process as the right route instead.
Our Visa guide says operators see a disputed real deposit as a breach of the terms. A player who charges back a payment they authorised can expect closure and a forfeited balance. A casino chargeback canada claim on a real deposit therefore puts the account at risk.
The casino answers with evidence. Player Protection Legal says casinos fight a casino chargeback canada claim to avoid losing revenue. The same source says they send the bank proof that the player agreed to the terms and gambled with the money.
Allyspin’s English terms say, in clause 9.5, that the company keeps the right to tell others about suspected fraud. The list covers other online casino operators, banks, payment processors and financial institutions.
For what a closure does to a balance, a pending payout and a bonus, read our casino account closure guide.
Does a casino chargeback canada claim follow you to other operators?
It can, our guides say: payment networks share the record, and one brand’s ban can follow you to its sister sites. Our credit card guide says a casino chargeback canada claim can affect a player at other operators too.
Our Visa guide warns that a claim filed in frustration can end access to far more operators than the one disputed. Our guide to blacklisted casinos names a chargeback as a common reason a licensed casino closes an account.
In most cases, casinos in one group share closure decisions. So a casino chargeback canada filing at one brand matters to its sister sites too.
Operators react hard because chargebacks cost them money, as the blogs written for operators explain. Chargeback Gurus says card networks and acquirers can fine merchants whose chargeback ratio passes a threshold, in most cases around 1%. PayShield says high ratios can bring higher processing costs, fines and even the loss of a merchant account.
FINTRAC’s special bulletin on online gambling lists indicators for licensed sites. One is a chargeback notification on the instrument used for a deposit, which it ties to unauthorised use. So a licensed site has a reason to treat a casino chargeback canada claim as a warning sign.
Before you file anything, look at who owns the casino.
Casino chargeback canada: which payment methods can you dispute?
The payment method you used decides your dispute route: a formal chargeback process belongs to card networks, and other methods use their own route. Player Protection Legal says the chargeback is mainly tied to card networks, both credit and debit.
| Payment method | Dispute route | Can it be reversed | Stated by |
|---|---|---|---|
| Credit or debit card | Formal chargeback process through the card issuer | In certain cases; credit has chargeback rights that debit lacks | Our payment methods guide, our scams guide, Player Protection Legal |
| Interac e-Transfer payment | The casino’s own complaints procedure, with no card chargeback | Our guides say Interac disputes offer a prospect of recovery | Our payment methods guide, scams guide and Neosurf guide |
| E-wallet such as PayPal | The wallet’s own dispute process, or the card issuer if card-funded | Not under PayPal Purchase Protection, which excludes gambling | Our PayPal guide, PayPal and Player Protection Legal |
| Cryptocurrency transfer on a blockchain | No dispute route, because a blockchain payment has no chargeback mechanism | Effectively irreversible, our guides say | Our crypto guide, scams guide and Litecoin guide |
| Prepaid voucher such as Paysafecard | The operator’s own complaints procedure | Nothing can be reversed later | Our Paysafecard guide and payment methods guide |
| Bank transfer or wire | Recall in limited circumstances, but no chargeback | Hard to recall, and no chargeback is possible | Our bank transfer guide and payment methods guide |
Read the table before you open a casino chargeback canada dispute, because each method has its own route. Our scams guide says recovery depends almost entirely on how you paid. Our guide to casino payment methods covers the card, Interac and voucher routes side by side.
Cards: the route with a formal process
A card is the one method here where a casino chargeback canada dispute follows a formal process run by the issuer. Our scams guide says credit cards have chargeback rights that debit cards and transfers do not. It adds that Canadian issuers decline gambling payments frequently.
If you charge back a deposit at a legitimate operator, the casino account is closed. So a casino chargeback canada dispute has a cost. Our PayPal guide says gambling is outside PayPal Purchase Protection. PayPal adds that card chargeback rights can be broader than Purchase Protection.
Prepaid cards are a different case. Our Visa guide says gambling sites frequently exclude prepaid cards to reduce chargeback and fraud exposure. FINTRAC calls prepaid cards and vouchers high-risk funding methods for online gambling.
Interac and bank transfers: the casino complaint route
Interac e-Transfer has no card chargeback, so a casino chargeback canada claim has no card network to go through. Our payment methods guide says Interac and vouchers depend on the operator’s complaints procedure instead. Our scams guide says Interac has a dispute process that can help in certain cases.
A bank transfer works differently. Our bank transfer casino guide says you cannot charge back a wire, and it is difficult to recall. Our payment methods guide adds that bank transfers offer recall in limited circumstances.
Our Interac casino guide links most exclusion clauses to chargeback risk, and says a bank transfer carries none. That is why a casino chargeback canada question also shapes bonus terms. Stronger dispute rights do not make a method better overall.
E-wallets: the wallet decides the dispute
In a casino chargeback canada case, the wallet’s own terms set the limits. Our PayPal casino guide says a player has to pick one route: a PayPal dispute or the card issuer’s dispute. The same guide says PayPal can delay a withdrawal after a chargeback, bank reversal or buyer dispute undid earlier payments.
Under Section 28 of the iDebit terms, a payment through iDebit is final and cannot be reversed. Section 47.4 bars charging back money that iDebit took from your bank. Claims about unauthorised payments go to your own bank under Sections 25.1 and 26. Section 28 adds that merchant disputes are not iDebit’s responsibility.
Clause 9.3 of the MiFinity terms rules out chargebacks on uploads, unless the use was unauthorised or MiFinity was in breach. A chargeback under that clause carries a fee of €25 plus any costs MiFinity incurs. The fee is written into the same clause. Count that fee in any casino chargeback canada attempt made through MiFinity.
Crypto and vouchers: no way back
Our guide to crypto at online casinos says money sent to a wrong address is gone for good. No bank or support ticket can bring it back. The guide adds that crypto takes away the chargeback protection a card deposit gives you. That makes a bad operator more dangerous, not less.
CoinJar states that crypto has no chargeback, so a casino chargeback canada request has no route after a crypto payment. Our Shiba Inu casino review makes the same point: a confirmed transfer is final.
Paid by voucher? For a casino chargeback canada question on that route, start with our guide to voucher payments. Name the payment method first, because the route you can use depends on it.
Which body handles which complaint?
The casino handles its own complaints, the card issuer handles a chargeback, and a licensing authority or dispute service handles casino complaints. A dispute service looks at a complaint about the casino itself. OBSI deals with how your bank handled your problem. Keep those four roles apart in any casino chargeback canada case.
OBSI says you can contact it if your bank’s work on your problem leaves you unhappy. The Financial Consumer Agency of Canada says a federally regulated institution has to fully investigate any disputed transaction. In a casino chargeback canada case, that duty rests with the institution, not the casino.
A refused withdrawal is a different case. Our credit card casino review says such disputes belong with the licensing authority, not the card issuer. Take that kind of complaint to the licensing authority. The Bank of Canada does not take on individual consumer disputes either.
Our scam guide says an offshore licence sends complaints to a body in another jurisdiction. There is no Canadian enforcement and no provincial dispute service, and no local authority can force payment. The same guide says to report fraud to your bank or payment provider, which can reverse recent payments in certain cases.
What do you try before a casino chargeback canada claim?
Try four steps in order before you file a chargeback: support, the casino complaint process, a dispute service, and then your bank. Our Visa guide says support resolves genuine errors routinely, and in most cases a problem ends before a chargeback is filed.
- Write to casino support and keep a record of the replies.
- Use the casino complaint process and wait for its decision.
- Go to the licensor or an independent dispute service.
- Call the bank only for unauthorised payments.
Step 1: write to casino support
Write to support first, long before any casino chargeback canada plan, and say plainly what went wrong. Vellis says to talk to support directly and to read the terms before you play.
Chargeback Gurus, another blog for casino operators, says quick, professional replies can stop a dispute before it becomes a chargeback. Do not hold a chargeback over the casino as a threat. Attach your deposit receipts, the KYC confirmation and screenshots of the terms you dispute.
Step 2: use the casino complaint process
Our guide to choosing a safe casino says a good complaints procedure acknowledges receipt, states a deadline and names the escalation route. Use that procedure before you think about a casino chargeback canada claim.
The AGCO route, as our casino withdrawal time guide sets it out, has three steps. Check the terms, follow the formal complaints process, then wait for the decision. The AGCO helps only with regulated sites, and it says to settle a dispute directly with the gaming site.
Step 3: go to the licensor or a dispute service
Our fast payout guide lists three steps: support, a complaint to the licensor, then the dispute service the licence names. Our blacklisted casinos guide says a filing with the regulator, Casino.Guru and AskGamblers at once can recover money in certain cases. Keep a casino chargeback canada claim for after these steps.
Under Curacao’s LOK framework, licensed operators need an ADR provider. Unsettled complaints go there at no cost, says our guide to legit online casinos. An ADR entity can be a faster, more direct route for a disputed payment. One review site warns that a dispute service has no power to make a casino pay.
Step 4: call the bank about unauthorised payments
Call the bank only when a card payment left your account without your approval. Our credit card casino guide says any other card deposit dispute belongs with the casino first and the licensing authority second.
The bank is not the first stop for a casino chargeback canada problem. Our guide to spotting casino scams says disputes go to the casino’s complaints process or the regulator before the card issuer.
Why is a chargeback the last step and not the first?
A chargeback wipes out every remedy the regulator offers, our safe casino guide says, so the complaint route comes first and the chargeback last. Our fast payout guide calls a casino chargeback canada claim the last resort with consequences. Our safe casino guide says a chargeback fits a fraudulent transaction, not regret over how play went.
OBSI says it does not recommend compensation in most cases where the consumer skipped the merchant or challenged the charge late. A no-verification casino removes the chargeback route a card gives the player, says our no-verification casino guide. A chargeback defence depends on the same evidence.
Casino chargeback canada: what do five casino pages say?
Five casino pages in our list carry lines about card ownership, refunds or chargebacks, and the sections below cover each one. These are the lines that the clause table does not already hold.
Allyspin: card ownership and suspected fraud
Allyspin’s English terms list a warranty that the card you use to fund your account belongs to you. The casino can close the account and void winnings if it has a reasonable suspicion of a breach.
Two more Allyspin clauses matter in a casino chargeback canada case. Allyspin’s terms say that if you funded your account by credit card, it can pay withdrawals back as refunds, up to the total deposited. It can also cancel a withdrawal when it suspects fraud, collusion or illegal activity. You can read more in our Allyspin review.
Dudespin: the same terms wording and a refund line
Dudespin’s English terms use the same ownership warranty: the funding card needs to be yours. Dudespin also reserves the right to close the account and void winnings after a reasonable suspicion of a breach. Withdrawals can be cancelled on suspected fraud, collusion or illegal activity.
In a casino chargeback canada dispute, Dudespin’s terms let the casino inform government bodies, other casinos and banks of suspected fraud. Our Dudespin review says withdrawals up to the deposited total can come back as refunds for card deposits.
Spinko: failed deposits and a chargeback indemnity
Spinko’s English terms do not allow a payment method that belongs to a third party. They name family members and company or business accounts as examples. Deposits made that way count as invalid, and the winnings from them are void.
For a casino chargeback canada case, the failed deposit clause is worth knowing. The terms count a deposit that fails, or that you or a third party cancel, as a Failed Deposit. In that case, Spinko is allowed to void the balances, bonuses and winnings tied to it. Open our Spinko review for more.
Ice Casino: ownership, third-party deposits and fraud
Ice Casino’s English terms ask you to confirm that you rightfully own the money in your account. They also say the details you give match the name on the card or payment account you use.
For a casino chargeback canada dispute, the third-party and reversal lines matter. Ice Casino does not accept third-party deposits, such as a friend, relative or partner. The terms also forbid any attempt to reverse a payment you made into the account. Breaking that term leads to account closure. See our Ice Casino review.
Gamblezen: a reviewer flags negative balances
Our Gamblezen review says a Casino Guru reviewer flags that an approved chargeback can push a balance below zero.
That is one way a casino chargeback canada claim can cost the player money. Our review of Gamblezen advises keeping balances small and cashing out regularly.
Can a recovery service get your casino money back?
A firm that offers to get your gambling losses back for an upfront fee is a warning sign, not a solution. Real help comes from your bank, the regulator or a dispute service.
A casino chargeback canada claim is a separate matter from a recovery offer. Our guide to casino scams says recovery scams go after people who have lost money. They ask for an advance fee and use lists of earlier victims.
An unprompted offer to run your casino chargeback canada claim for a fee is a second scam. The offer comes from a stranger who contacts you after the loss.
Our guide to blacklisted casinos tells you not to pay a third-party recovery service. In most cases they are scams, and a second payment deepens the damage.
A police report for fraud against a blacklisted casino is possible when you hold proof. A lawyer can sue, but in most cases international law and the cost make that impractical.
Player Protection Legal, a UK law firm, says its service for player disputes runs on a no-win-no-fee basis. That is the firm’s own offer and a UK service. This page does not recommend any firm for a casino chargeback canada claim. Ask for the fee terms in writing before you agree to anything.
Which red flags surround a casino chargeback canada claim?
Red flags are signs that a firm or casino wants your money first, hides its rules or pushes a false claim. These six signs separate a real dispute from a trap.
- A fee before any action. A firm asks for money before it acts on your casino chargeback canada claim. A genuine service does not ask fraud victims for advance payment.
- A push to fund by card, then dispute. In certain cases a fraudulent site urges you to fund your account by card and then dispute the payment. The operator keeps the balance, and you face fraud allegations.
- A script about authorisation. Someone tells you to say you did not authorise a payment that you made. Friendly fraud is still fraud, as Vellis says.
- No licence and no one above it. The casino has no licence, no public procedure and no outside body to appeal to. A real dispute needs a licensed operator and a clause you can quote.
- Terms that change mid-dispute. Our fast payout guide calls a mid-dispute rewrite the clearest warning. A dated screenshot from day one can show what the terms said.
- No clause named. The casino will not name the clause it relies on. You cannot escalate a rule that nobody shows you, so ask for it in writing.
A casino chargeback canada claim against a legitimate operator carries a price. Our guide to casino scams says a chargeback against a legitimate operator closes your account and forfeits the funds. Ask first whether the casino broke a clause you can name. Weigh that price before you file anything.
What are the pros and cons of a chargeback versus a casino complaint?
A chargeback is a bank tool for unauthorised or undelivered payments, while a complaint to the casino covers play, bonuses and payouts. A casino chargeback canada claim starts with picking the right tool, since the two do different jobs.
What are the pros of a chargeback?
A chargeback puts your bank in charge of the file and gives the claim a fixed set of rules. The pros below apply when the payment was unauthorised or never delivered.
- The bank handles the file, and OBSI says the bank refunds the amount in most cases while it investigates.
- OBSI says network rules can protect you, and strict timelines apply to a casino chargeback canada claim.
- Cards carry rights that crypto and vouchers do not, as our guides explain.
- OBSI reviews how the bank handled your problem if you are unsatisfied with its efforts. It says card charge disputes are among the most common banking complaints it receives.
What are the cons of a chargeback?
A casino chargeback canada claim has costs for your account, your time and your record.
- Play that you chose and lost is outside what a chargeback covers.
- Our credit card guide says a chargeback closes the account and forfeits the balance at most operators.
- The record of a casino chargeback canada claim is shared across payment networks, our credit card guide says.
- Player Protection Legal says an investigation takes around 30 days in most cases and up to 90 in complex ones. OBSI says the refund can be reversed.
Before you file a casino chargeback canada claim, know what OBSI weighs in card disputes. It says the outcome depends on the evidence each side can show. In most cases it does not recommend compensation if the client waited too long or skipped the merchant first.
The same list names a PIN that was not protected and a client who did not cooperate with the bank. So a bonus or payout dispute belongs in a casino complaint before it reaches the bank.
When is gambling the reason you want your money back?
If gambling losses are why you want your money back, no chargeback fixes that, so talk to a person who can help. A casino chargeback canada claim is for payments you did not authorise or never received, not for play you chose.
A spending limit holds your play at the amount you chose, and a time-out pauses play for a set period. Our gambling limits guide shows how to set limits, and our self-exclusion guide explains how to step away for longer. Set it before you play, not after a loss.
You can call ConnexOntario on its helpline at 1-866-531-2600, the number our Mastercard guide gives. A short deadline or a big loss is a reason to stop and talk, never a reason to chase play.
Frequently asked questions about casino chargeback canada
A chargeback can reverse an unauthorised or undelivered card payment, and the short answers below cover the questions readers ask most. Each answer points to the section of this page with the detail on casino chargeback canada.
Can I charge back a casino deposit in Canada?
Yes, but only for certain payments, such as an unauthorised charge or something paid for and never delivered. The bank or card issuer decides, not the casino, and it works for cards only.
Does a casino chargeback canada claim work for a normal loss?
No, a normal loss is not a reason for a chargeback. Losing a bet you placed is not an unauthorised or undelivered payment, so the bank has no ground to reverse it.
What happens to my casino account after a chargeback?
In most cases the casino closes the account and forfeits the balance after a casino chargeback canada claim, our guides say. Our casino account closure guide explains what closure means for your funds.
Who do I contact first, the casino or the bank?
Contact the casino first, using its complaint process, and then the card issuer if the problem stays open. If you never approved a payment, tell your bank at once.
Can I charge back a crypto deposit?
No. CoinJar notes that crypto has no chargeback. A casino chargeback canada claim needs a card issuer to review it, and a crypto transfer has none.
What is friendly fraud, and why is it a bad idea?
Friendly fraud means claiming that a payment you made yourself was unauthorised, and that claim is fraud. If the problem is real, use the casino’s complaint process instead.
Does OBSI handle disputes with casinos?
No, OBSI reviews only disputes between a consumer and their bank, not with a merchant. A casino chargeback canada dispute with the casino itself falls outside its work.
How long does a casino have to answer a card dispute?
Amex Canada’s brochure gives the merchant 20 days from the inquiry letter. If the merchant stays silent, Amex debits the amount. Amex can issue a chargeback without a letter for merchants with high dispute counts. Its Gold Rewards agreement has the cardholder settle with the merchant.
Will a chargeback block me from other casinos?
It can, our guides say, because the record can travel across operator networks and sister sites. So a casino chargeback canada claim at one site can follow you to the next.
Can a company get my gambling losses back for a fee?
No. An offer that wants payment before it acts is a warning sign. Our guide to casino scams lists the warning signs to look for.
Where can I get help if gambling is the problem?
Call ConnexOntario on its helpline, 1-866-531-2600. If gambling is hurting your money, mood or home life, make that call before you chase a refund, not after.